Blask Data Paints Clear Picture of UK iGaming Shifts in May 2026
Blask released its latest brand power rankings for May 2026 and the numbers place Bet365 at the top with 12.59 percent share while Ladbrokes, William Hill and several other operators trail in close pursuit. The report positions Entain and Flutter as the dominant forces when viewed through a group-level lens and this hierarchy emerges against a backdrop of regulatory adjustments that took effect in April 2026.
Brand Power Rankings Break Down the Competitive Field
Data from the analysis shows Bet365 holding the single-brand lead at 12.59 percent and the next positions belong to Ladbrokes and William Hill with additional operators filling out the remainder of the top tier. Observers note that these rankings rely on accumulated brand-power metrics and Competitive Earning Baseline calculations and the figures reveal a market where individual brand strength continues to matter even as larger corporate groups consolidate influence. Entain and Flutter sit atop the group standings and their combined reach spans multiple consumer-facing properties that together command significant portions of player attention adn revenue.
Online Casino Sector Posts Strong Monthly Gains
Online casino recorded a 14.03 percent month-on-month increase in May 2026 and this expansion occurred even after the remote gaming duty rose to 40 percent the previous month. Most major brands experienced monthly declines in their individual metrics yet the category as a whole advanced and analysts attribute part of the resilience to sustained year-on-year growth patterns that persisted through the tax change. The report highlights that several leading operators maintained positive trajectory when compared with the same period in 2025 and this continuity suggests underlying demand remained robust despite higher operator costs.
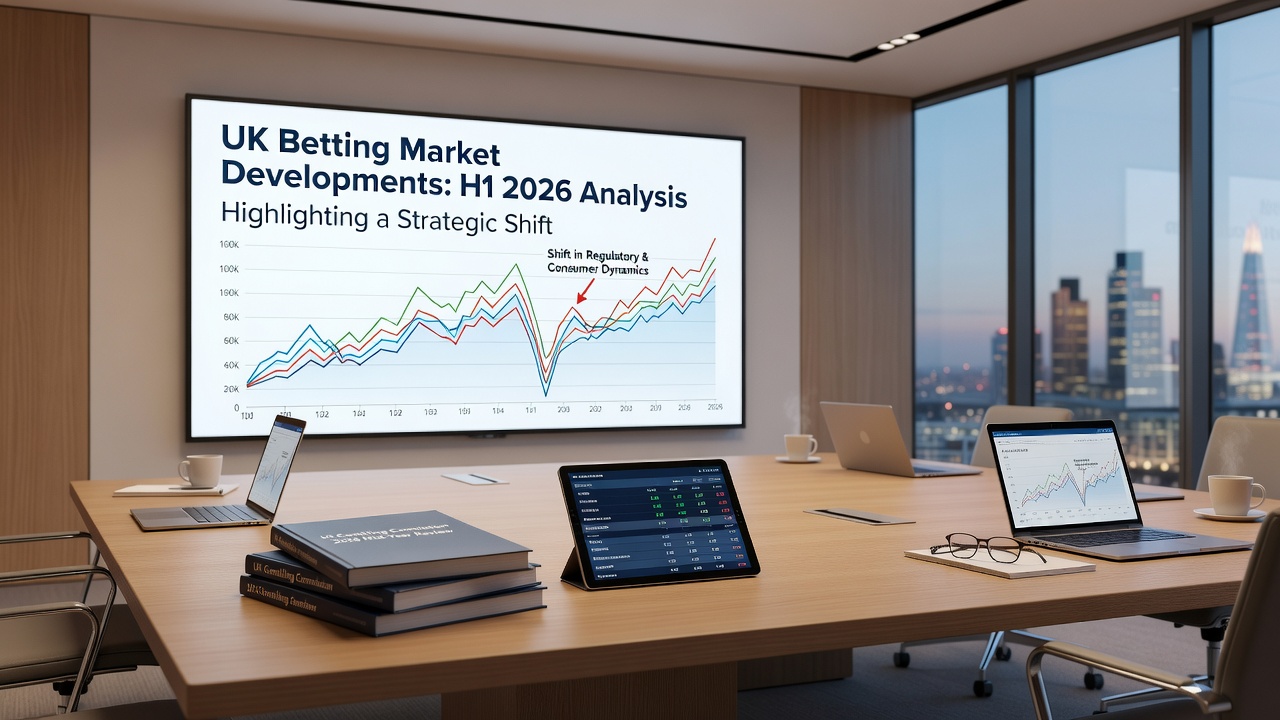
Those who track the sector point out that the duty increase did not halt category expansion and instead coincided with measurable growth that outpaced many individual brand results. Figures reveal the sector adapted quickly and the data captures how player activity concentrated in online casino offerings during the period.
Player Demographics Reveal Young Digital-First Audience
Blask analysis identifies a player base that skews young and digital-first with 15 percent of participants classified as moderate-risk or problem gamblers. The report ties this demographic profile to broader engagement trends and notes that the same cohort drives much of the observed category growth. Researchers tracking these patterns observe that digital-native users interact with platforms differently from older segments and the concentration of activity within this group helps explain why online casino metrics advanced while certain legacy brands recorded softer monthly figures.
Evidence from the data set shows continued year-on-year expansion for multiple top brands even after the tax adjustment and this performance occurs alongside the documented risk distribution. The 15 percent moderate-risk or problem-gambler classification appears as a stable characteristic within the measured population and the report presents it as context rather than a new development.
Tax Changes Frame the May 2026 Results
The April 2026 remote gaming duty increase to 40 percent serves as the immediate backdrop for the May numbers and operators across the market absorbed the higher rate while online casino still posted double-digit growth. Data indicates that brand-level declines among many major names did not prevent category-level gains and the report connects these outcomes to ongoing structural shifts in how players access and spend within iGaming environments. Year-on-year comparisons within the Blask figures demonstrate that several leading operators preserved or extended their positions relative to 2025 and this resilience stands out given the altered cost structure.
Those examining the Competitive Earning Baseline metrics find that group-level dominance by Entain and Flutter persists through the period and the single-brand leadership of Bet365 reflects concentrated consumer preference within its vertical. The report stops short of forecasting future months and instead supplies the snapshot for May 2026 as a reference point for market participants.
Conclusion
Blask's May 2026 release supplies a concise overview of brand standings, category performance and player characteristics at a moment when the 40 percent remote gaming duty had recently taken effect. Bet365's 12.59 percent lead, the group-level strength of Entain and Flutter, the 14.03 percent online casino increase and the 15 percent moderate-risk classification together form the core findings. Observers can reference the full dataset for additional detail on how these elements interact within the current regulatory setting.