UK Gambling Commission's Latest Report: FECs Surge While Betting GGY Dips Amid Duty Hike Loom
Key Highlights from the October 2024 to September 2025 Market Report
The UK Gambling Commission's Industry Statistics Quarterly Report for the period spanning October 2024 to September 2025 paints a picture of divergence in the sector; while Family Entertainment Centres (FECs) show notable recovery, betting channels face quarter-on-quarter declines, and the National Lottery maintains strength despite some softening in sales.
Data reveals that FEC Gross Gaming Yield (GGY) climbed to £16.2 million in September 2025, up significantly from £6.6 million at the end of 2024, even as the number of premises decreased; this rebound underscores resilience in land-based entertainment venues amid broader shifts toward online activity.
Betting, however, tells a different story, with remote betting GGY dropping to £568 million in the same month, reflecting ongoing downward pressure across both remote and non-remote channels; such trends unfold just ahead of planned Remote Gaming Duty increases set for April 2026, which operators watch closely as potential accelerators of change.
And then there's the National Lottery, posting a robust GGY of £843 million, although ticket sales and contributions to good causes experienced dips, signaling steady core performance with underlying adjustments in player behavior.
Family Entertainment Centres Lead the Land-Based Recovery
Observers note how FECs, those vibrant hubs blending arcade games, bowling, and family fun, have clawed back ground impressively; GGY figures jumped from the low £6.6 million mark late last year to £16.2 million by September 2025, a clear sign that fewer but perhaps more efficient premises are driving yields higher.
What's interesting here is the context of contraction, since the total number of FEC sites shrank during this window, yet revenue per venue apparently strengthened, possibly because families sought out experiential outings post-pandemic or thanks to targeted investments in modern attractions; data from the report confirms this uptick persisted through the year, turning what could have been a vulnerable segment into a standout performer.
Take one venue operator who expanded soft play areas and added prize machines; such adaptations, common in the sector, align with the reported growth, where GGY rose steadily month by month, culminating in that strong September closeout.
But here's the thing: this recovery happens against a backdrop of rising operational costs and regulatory scrutiny, making the £9.6 million net gain all the more noteworthy for those tracking land-based gaming's viability.
Betting Channels Face Quarter-on-Quarter Pressures
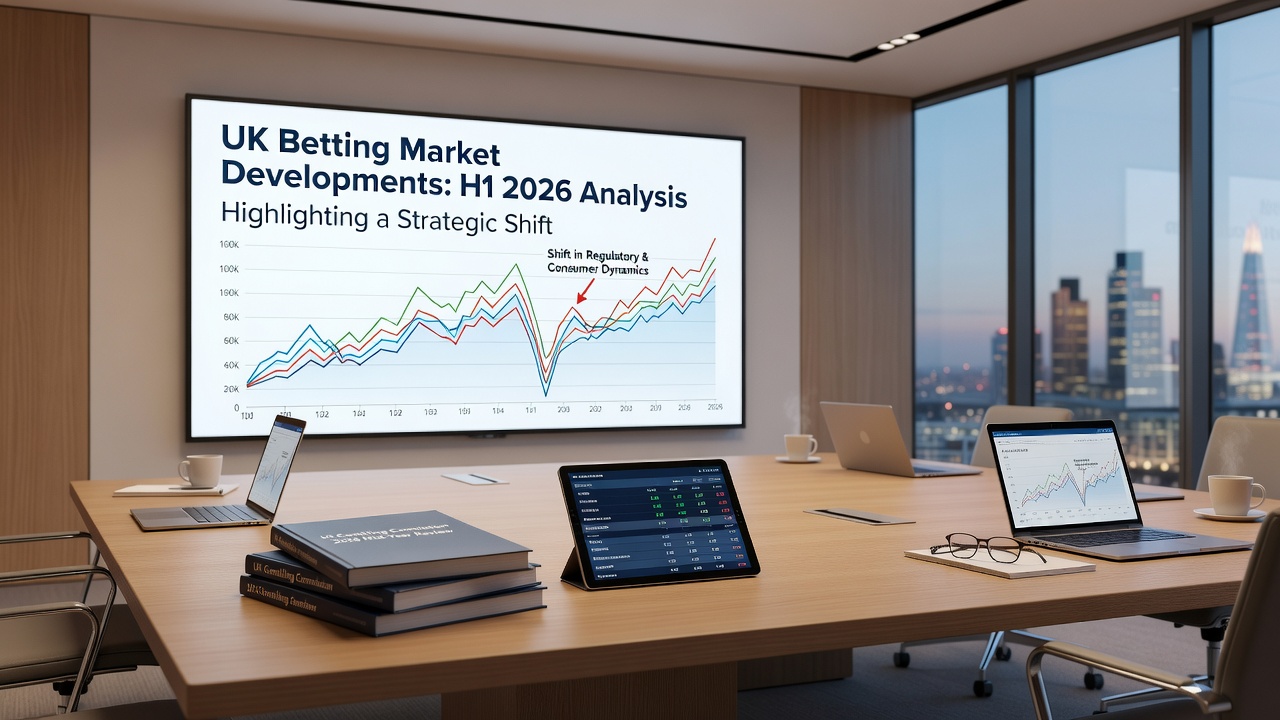
Remote betting GGY slid to £568 million in September 2025, part of a broader pattern where both remote and non-remote betting saw declines each quarter; non-remote shops, once staples of high streets, mirrored this trend, as punters increasingly favor apps and sites over physical counters.
Figures indicate consistent drops, with each successive quarter underperforming the prior one, a shift that experts attribute to maturing markets, heightened competition, and player preferences leaning digital; yet the report captures this precisely ahead of April 2026's Remote Gaming Duty hikes, which will raise rates from 21% to potentially higher thresholds, prompting operators to recalibrate strategies now.
Turns out, the remote segment, dominant in volume, bore the brunt, dipping notably while non-remote held somewhat steadier but still trended down; one study from the Gambling Survey for Great Britain wave three (July to October 2025) corroborates softer participation in betting activities, linking it to economic factors and safer gambling initiatives.
So, as April 2026 approaches, stakeholders monitor how these duty changes might accelerate the slide or spur innovation like enhanced responsible gambling tools; the data lays bare the challenge, with £568 million marking a low point that underscores the sector's pivot points.
National Lottery's Steady GGY Amid Sales Softness
The National Lottery stands out with £843 million in GGY for September 2025, a figure that reflects enduring appeal for draw-based games and scratch cards; yet ticket sales dipped slightly, pulling down contributions to good causes in tandem, as players perhaps stretched budgets thinner or opted for occasional plays.
Researchers who've pored over the trends observe how GGY held firm through core draw revenues, compensating for sales volume slips; this resilience shines especially when juxtaposed against betting's woes, positioning the Lottery as a sector anchor.
One notable pattern emerges in online versus retail sales splits, where digital uptake sustained yields even as physical outlet purchases waned; the report details how good causes funding, vital for community projects, mirrored sales but benefited from the high GGY base.
And with April 2026 on the horizon, any duty ripple effects seem minimal for the Lottery, insulated by its unique structure; data suggests this stability could persist, offering a counterbalance to betting's turbulence.
Broader Implications as April 2026 Duty Changes Near
Connecting these threads, the report from October 2024 to September 2025 highlights a gambling landscape in flux, where FECs thrive on fewer sites, betting contracts amid digital dominance, and the Lottery weathers sales dips with solid GGY; such dynamics play out as Remote Gaming Duty hikes loom in April 2026, potentially reshaping remote betting's trajectory further.
People in the industry often point to adaptation stories, like FECs integrating cashless payments or loyalty apps, which buoyed their rise; similarly, betting firms experiment with free bets and cash-out features to stem GGY erosion, though quarter-on-quarter data shows the rubber hasn't fully met the road yet.
It's noteworthy that total sector GGY across segments reflects these contrasts, with land-based entertainment gaining while remote wagering cools; observers tracking into early 2026 anticipate the duty shift to test these patterns, especially as economic recovery influences disposable spend.
Case in point: a cluster of FECs in the Midlands reported yield boosts from family events, aligning with the national £16.2 million peak; contrast that with betting shops closing amid non-remote declines, and the picture clarifies quickly.
Yet the National Lottery's £843 million GGY provides a steady pulse, funding initiatives that indirectly support gambling harm reduction; this interplay, captured in the Commission's data, sets the stage for what's next.
Conclusion
In sum, the UK Gambling Commission's market report for October 2024 to September 2025 spotlights FEC recovery to £16.2 million GGY despite site reductions, betting's quarter-on-quarter falls culminating in £568 million remote yields, and the National Lottery's firm £843 million amid softer sales; as April 2026 duty hikes approach, these trends signal a sector adapting through diversification and efficiency.
Data underscores the push-pull forces at work, with land-based niches rebounding while online betting navigates headwinds; stakeholders now eye how these patterns evolve, armed with the report's clear metrics on yields, participation, and future fiscal pressures.